Person annotating a printed analytics report beside a laptop showing charts
EV FINANCIER CASE STUDY

30% Improved Buyer Confidence in EV Resale

How FawkesLink battery intelligence converted battery health into accurate pricing for EV resale.

Industry
EV Financiers
Product
FawkesLink
Published
September 4, 2026
← All case studies

India’s EV financing market is projected to exceed ₹3 lakh crore by 2030. More than 70% of commercial EV purchases are expected to involve financing. However, as the market matures, a key challenge emerging across financiers, lenders, fleets and vehicle owners is:

How do you accurately determine the value of a used EV?

Unlike traditional vehicles, where age, mileage and service history are reliable indicators of value, EVs derive a significant portion of their economic value from the battery system. However, battery condition is largely invisible, and OEM reported values vary from brand to brand.

This becomes a core problem for resale and refinancing transactions. To address this challenge, EVFin partnered with Fawkes Energy to build a standardized battery intelligence driven workflow for used EV assessment, valuation and financing.

The partnership began with a pilot involving 60 electric two-wheelers, where FawkesLink was deployed to assess battery health, estimate remaining useful life and generate battery-aware resale valuations.

The results demonstrated a critical market need: Battery transparency improves buyer confidence, supports more accurate pricing and enables better financing decisions. This pilot is now laying the foundation for a much larger vision: creating the asset intelligence infrastructure required for India's EV financing ecosystem.

The Problem

Battery Condition is invisible

Two vehicles of the similar odometer readings, age and service history can have differing battery health and performance. For example:

Vehicle A

  • 30,000 km
  • 92% SoH
  • 5-6 years Remaining Useful Life

Vehicle B

  • 30,000 km
  • 84% SoH
  • 3-4 years Remaining Useful Life

These differences arise from usage patterns, charging habits, driving, and operating environment, and sometimes from manufacturing defects. All of it is invisible to a basic manual inspection.

Guarantee and Refinancing Decisions Lack Data

Lenders hesitate to refinance used EVs without a clear picture of remaining battery life, degradation trajectory, future maintenance costs, or expected range performance. A pack degrading faster than assumed drives up maintenance and replacement costs and raises the odds of default or a shortfall at recovery. Repeated across a book of thousands of vehicles, those blind spots compound into real portfolio risk the lender cannot see or price.

Lack of Standardized Battery Valuation

Traditional ICE vehicle valuation runs on shared standards: age, mileage, and brand. Electric vehicles have no such common yardstick for battery health. Every OEM calculates State of Health differently and the figures that are reported are not comparable or consistent across brands. The battery state, which is the key determinant of value, becomes the one metric financiers cannot consistently measure or trust.

The Opportunity

Industry studies indicate that the battery accounts for 35 to 50% of a two-wheeler EV's value and 40 to 60% of a three-wheeler's. That makes it the single largest lever on what these vehicles are worth, and today it sits almost entirely untapped in how they are priced and financed.

Battery intelligence turns the unknowns into visibility, creating an advantage:

  • sharper, evidence-based pricing
  • accurately priced risk premiums
  • stronger buyer confidence
  • deeper financing penetration
  • better-protected residual values

A trusted battery intelligence layer can have a ripple effect across the financing ecosystem.

What we built

We built FawkesLink, a portable hardware device that connects to a vehicle to measure battery health without any historical data required. A single short diagnostic session while charging captures the battery data, avoiding lengthy lab cycling tests or intrusive battery teardown.

FawkesLink works in three layers:

  • Hardware intelligence: The portable hardware device captures voltage, current, charge characteristics, thermal behaviour, and dynamic battery signatures.
  • Physics-informed analytics: Physics-informed machine learning converts those signals into State of Health, Remaining Useful Life, Range Prediction and degradation trajectory.
  • Financial intelligence layer: The engineering outputs become residual value estimates, asset risk scores, and pricing recommendations that a financing team can act on directly.

In practice the workflow is simple: a vehicle arrives for resale, refinancing, or recovery; FawkesLink is connected for a 60-minute charging session; the data is processed in the cloud against vehicle-specific and fleet benchmark data; and a Battery Health Report is generated.

‍

FawkesLink essentially reports on:

The State of Health: the core metric, showing how much of the battery's original capacity remains, measured against its as-new condition.
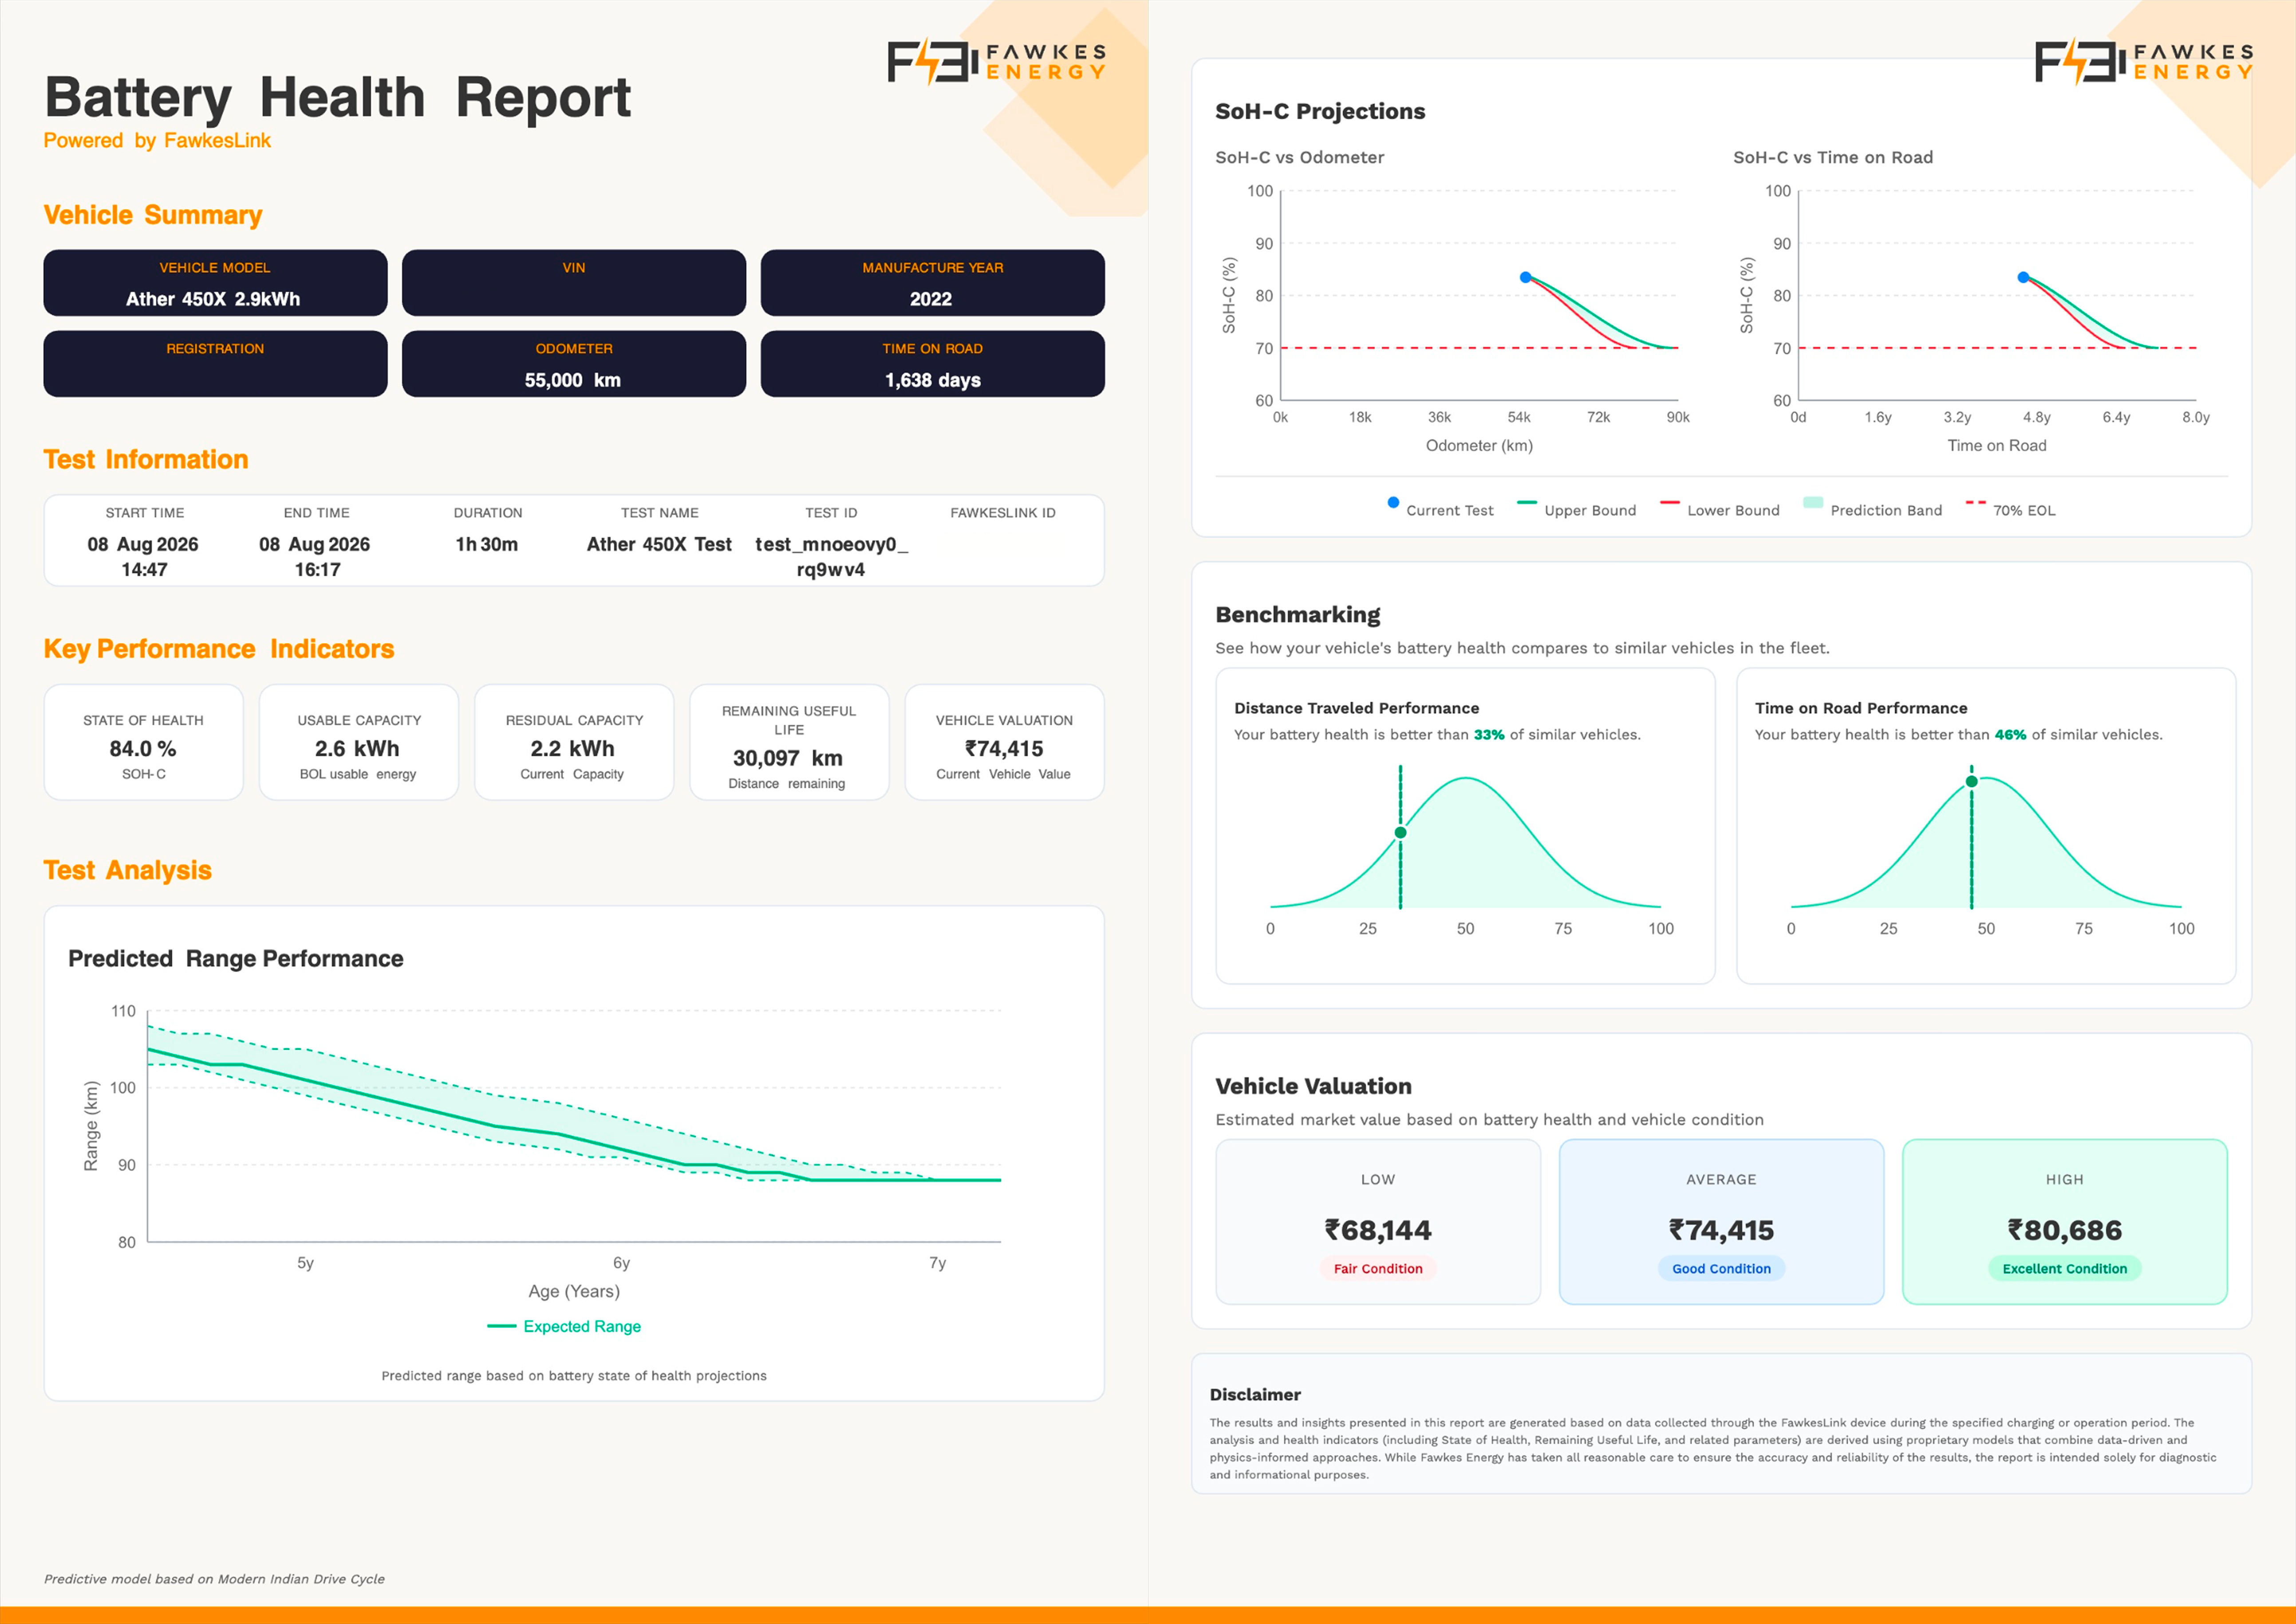
Remaining Useful Life
Range Prediction
Asset Benchmarking
Residual Value Engine
How much operational life the battery has left before it needs replacement or repurposing.
The real-world range the vehicle can deliver today, under typical operating conditions.
How the vehicle's battery compares to peers of the same model, age, and mileage.
A valuation that prices the vehicle on measured battery condition, not just age and odometer.
FawkesLink Sample Battery Health Report for 2 Wheeler EV

5 value drivers of battery intelligence for EV financing

1. 30% improved buyer confidence

Battery uncertainty is the single biggest hesitation for a used-EV buyer. A brand-neutral battery certificate removes that doubt, strengthens customer trust, and shortens the sale cycle: clear data minimizes negotiations and uncertainties, which means faster deals and shorter time spent in the yard. The impact: 30 to 50% improved buyer confidence

2. Faster data driven asset recovery

Every day a repossessed vehicle sits unresolved, it loses value and ties up capital. A battery assessment at the time of recovery attaches measured battery condition, so the asset moves straight through the resale channel instead of waiting on manual inspection, OEM reports and service history checks. This enables smarter recovery strategies and faster, standardized decisions across every asset.

3. Battery-condition-backed pricing and residual value

A residual value engine built on measured State of Health prices each asset on what the battery can still deliver instead of how far it has been driven. This results in a 25% improvement in data-backed pricing accuracy and a 30% improvement in residual value forecasting accuracy. For financiers managing tens of thousands of vehicles, even a 5 to 10% improvement in residual-value visibility can translate into crores of rupees in protected asset value.

4. Data-backed underwriting with calculated battery risk

Traditional underwriting runs entirely on borrower-side signals: credit score, income, vehicle age, and repayment history. Battery intelligence adds the asset side metrics that EV loans depend on: a Battery Health Score, Battery Degradation Rate, Predicted Failure Risk, Remaining Useful Life, Asset Liquidity Score, and Residual Value Forecast. Just as credit bureaus transformed consumer lending by standardizing borrower risk, this standardizes asset risk, letting lenders price each loan against the real condition of its collateral.

5. Dynamic, battery-aware loan-to-value models

Static depreciation assumptions break down for EVs, which depreciate differently and less predictably than combustion vehicles, changing with battery condition, warranty status, and maintenance requirements. A static curve either over-lends against a fast-fading asset or under-lends against a healthy one. Battery-aware depreciation curves replace the fixed schedule, so loan pricing, asset valuation, and risk assessment stay accurate throughout the asset lifecycle, adjusting LTV to the battery's true condition rather than its age.

Why it matters

Without Battery Intelligence:
Broad price ranges with no defensibility → Drawn-out price negotiations → Vehicles sitting idle in the yard

With Battery Intelligence:
‍
Data-backed pricing → Quantified asset life → Faster-moving decisions

The EV market is nearing an inflection point. Millions of vehicles financed over the last decade will soon move into secondary ownership, refinancing, and fleet-replacement cycles, and the industry still has no way to evaluate battery condition at that scale.

Just as credit bureaus reshaped consumer lending by standardizing borrower risk, battery intelligence stands to reshape EV financing by standardizing asset risk.

Looking ahead

This partnership reaches well beyond a diagnostic tool for resale. It lays the foundation for battery-aware financing, resale, and refinancing, and for standardized residual value models, moving toward a future where every battery carries a trusted, continuously updated health and risk profile: a battery credit score.

As EV adoption accelerates, battery condition becomes the single most important determinant of vehicle value and financing risk. FawkesLink helps lenders treat batteries as measurable financial assets rather than opaque components, and the result is a more liquid, transparent, and financeable EV ecosystem.

Fawkes Energy is not merely measuring batteries. We’re building the trust layer for the EV economy.

We're working with early partners across EV and BESS.
If batteries are central to your business,
let's talk
Let's Talk